A major initial public offering, or IPO, can be an important moment for a company and for the investment trusts that backed it before it joined the stock market.
An IPO does more than establish a visible market price for a previously private company. For investment trusts that have held the business, it can change how the holding is valued, managed and viewed by the market. Whilst a listing may bring greater transparency, it can also bring into sharper focus risks around concentration, share-price volatility and the ability to sell a holding immediately.
Investment trusts are collective investment funds publicly traded on stock exchanges that invest in a diversified portfolio of assets such as stocks, bonds and real estate. Unlike an open-ended fund, an investment trust does not typically need to sell assets when shareholders wish to withdraw funds. This structure supports a long-term approach, particularly where fast-growing companies choose to stay private for longer, but exceptional gains can push a holding beyond a manager’s preferred position size and increase concentration risk. Post-IPO lock-ups may then prevent the position from being fully rebalanced, even where there is a clear portfolio-management case for doing so.
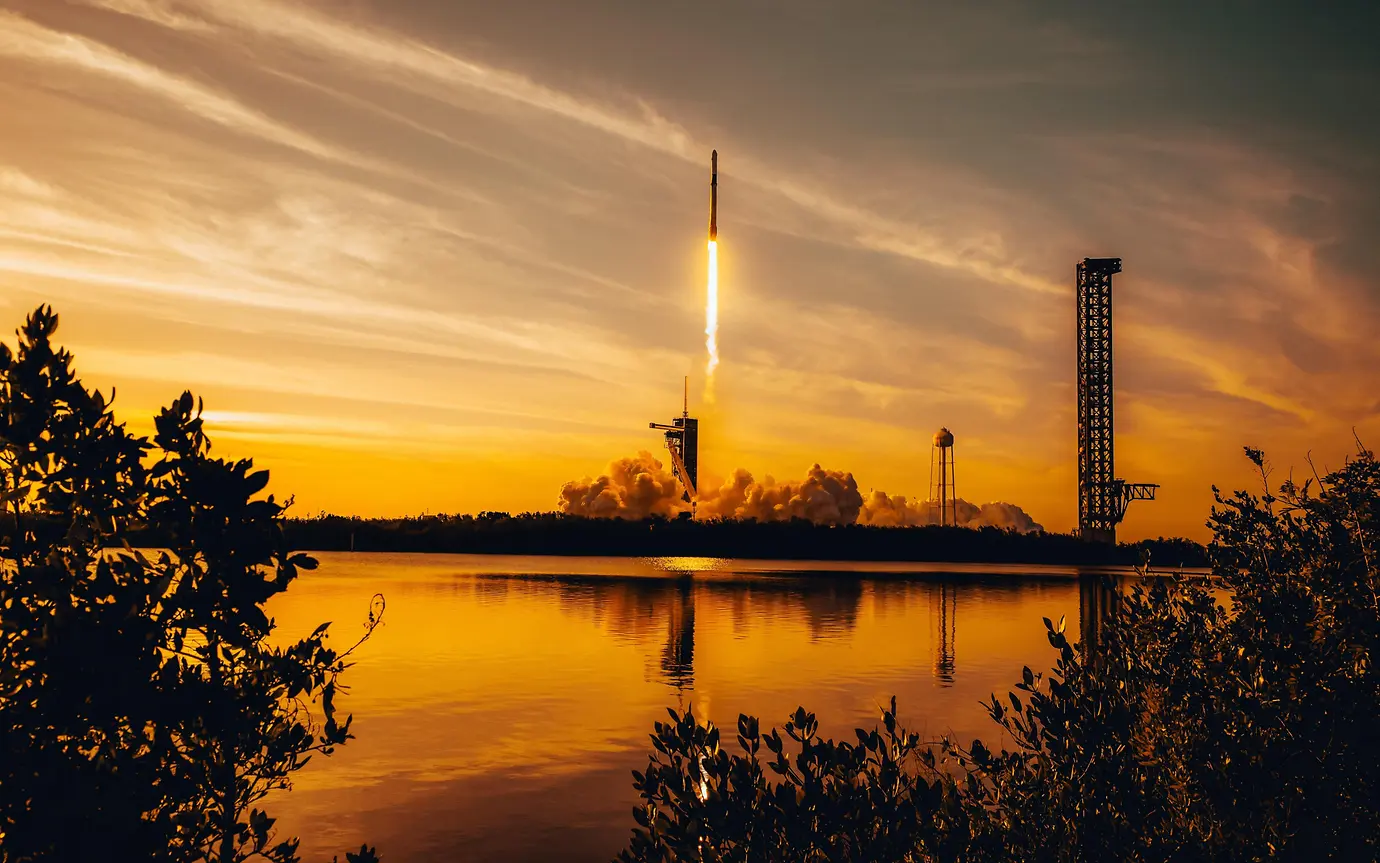
SpaceX’s June flotation established a quoted market value for holdings that had generated substantial gains for a small group of UK investment trusts, but also exposed a less obvious problem. An IPO creates a visible market price, but not necessarily immediate liquidity for early investors. With SpaceX now a significant position in several trusts, attention has shifted to how managers will respond as their shares become eligible for sale.
As more potential mega-IPOs approach public markets, SpaceX can offer an instructive test case in how investment trusts may navigate the move from private to public markets.
Before an IPO, private holdings are valued periodically rather than continuously priced. Managers typically take into account recent funding rounds, secondary transactions, listed-company comparators, operational progress and share-class rights. These assessments are usually subject to independent oversight.
After a company lists, its quoted share price will normally become the main reference point for the holding’s daily fair value and, therefore, into a trust’s net asset value (NAV). The NAV is the value of a trust’s assets minus liabilities and is usually calculated per share. The treatment may differ where shares remain restricted and a manager may conclude that an adjustment to the quoted price is appropriate during the lock-up period.
SpaceX initially traded materially above its offer price, later fell below it and had recovered to modestly above the offer price by mid-August. These movements illustrate that a visible market price does not remove market or concentration risk, particularly when a manager cannot yet sell all, or part, of the position.
SpaceX has become exceptionally important to several portfolios. Scottish Mortgage invested a cumulative £151 million between 2018 and 2021. By the end of March 2026, the holding was worth nearly £3 billion and represented over 19% of the trust’s total assets. This increased further following the IPO and early share-price rise, exceeding one-quarter of the fund at the end of June.
This illustrates how a successful long-term investment can become a dominant position within a trust. Whilst that can make a substantial contribution to performance, it also means that the trust’s future returns may become more dependent on the performance of one company.
SpaceX’s lock-up arrangements are more complex than those associated with a typical IPO, which often involves a single 180-day restriction. Its prospectus provided for portions of eligible pre-IPO holdings to become saleable in stages from August, with further time- and results-based releases and remaining applicable restrictions generally expiring after 180 days. This reduces the risk of simultaneous selling but prolongs the period during which managers cannot fully rebalance their exposure.
Different trusts’ responses illustrate different valuation and portfolio-management approaches. Before the flotation, Scottish Mortgage said that listing would change the trading venue, not its reasons for owning SpaceX. At its July AGM, however, the firm’s managers described the resulting concentration as unusual and said they would seek to address it as successive tranches became saleable. This signalled an intention to rebalance rather than a commitment to exit or follow a fixed disposal programme.
Schiehallion, another investment trust operated by Ballie Gifford, said SpaceX would be handled through its normal portfolio-construction process and did not commit to selling a specified amount.
RIT Capital Partners reclassified SpaceX from private investments to quoted equities following the flotation. It revalues the holding daily using the quoted share price, whilst applying an undisclosed discount during the period that the relevant shares remain locked up. As these restrictions expire, RIT will need to decide whether to retain or sell all or part of the position.
The implications extend beyond NAV. A trust’s share price is determined by demand for its shares and can move differently from the value of its underlying assets. A trust trades at a discount when its share price is below the value of its underlying assets per share, and at a premium when it is above that value. Investors may be willing to pay more for indirect access to a sought-after private company, but that scarcity value can diminish once the company is publicly listed. By way of an example, Scottish Mortgage moved from a material discount at the end of March to a premium ahead of the IPO.
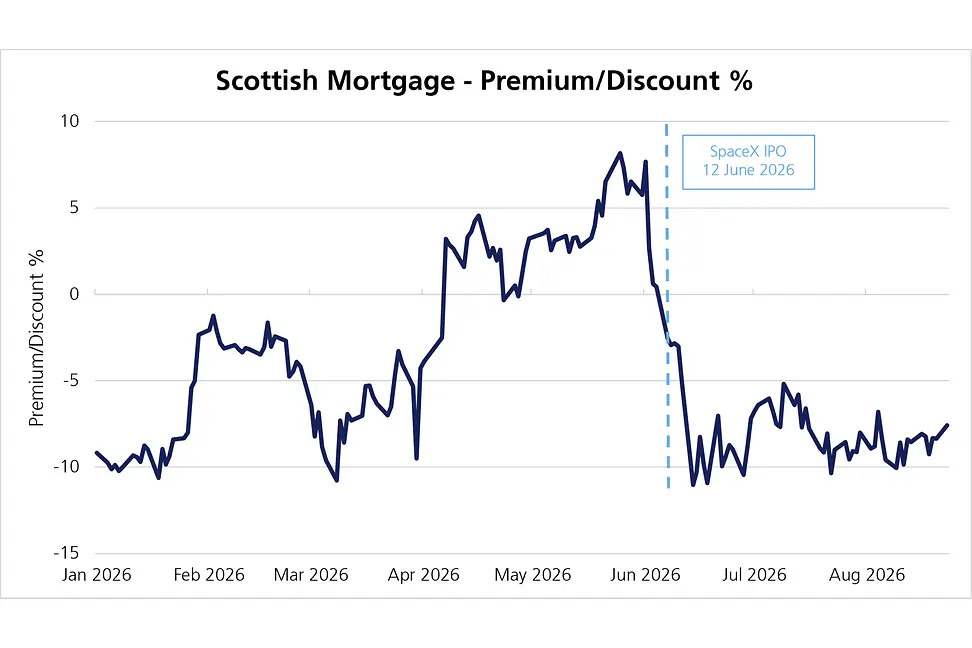
The SpaceX IPO, and other major IPOs likely to follow in the age of AI mega-cap companies, illustrates both the strengths and limitations of the investment trust structure. The structure enables patient ownership and exceptional gains before an IPO without redemption pressure, although the transition to public markets brings new challenges around valuation, liquidity and concentration. Irrespective of these issues, investment trusts can provide investors with access to some of the most exciting private companies well before they reach public markets. As more businesses remain private for longer, this ability to invest patiently in potential future IPO candidates and continue owning them beyond flotation, remains one of the structure’s most compelling advantages.
Sources
SpaceX final prospectus, June 2026
Scottish Mortgage final results, 27 May 2026
Scottish Mortgage AGM reporting, 2 July 2026
Schiehallion, “SpaceX update”, 19 June 2026
RIT Capital Partners, “SpaceX: key facts”, 8 June 2026
This communication is provided for information purposes only. The information presented herein provides a general update on market conditions and is not intended and should not be construed as an offer, invitation, solicitation or recommendation to buy or sell any specific investment or participate in any investment (or other) strategy. The subject of the communication is not a regulated investment. Past performance is not an indication of future performance and the value of investments and the income derived from them may fluctuate and you may not receive back the amount you originally invest. Although this document has been prepared on the basis of information we believe to be reliable, LGT Wealth Management UK LLP gives no representation or warranty in relation to the accuracy or completeness of the information presented herein. The information presented herein does not provide sufficient information on which to make an informed investment decision. No liability is accepted whatsoever by LGT Wealth Management UK LLP, employees and associated companies for any direct or consequential loss arising from this document.
LGT Wealth Management UK LLP is authorised and regulated by the Financial Conduct Authority in the United Kingdom.