The US midterm elections on 3 November will decide control of Congress for the final two years of President Donald Trump’s second term. With Republicans holding narrow majorities, a small number of seats could change the balance of power. Current expectations favour Democrats taking the House, with more uncertainty associated with the outcome of future Senate control.1 This event is one of the key milestones of the US political calendar in 2026, and with all eyes watching, it is likely to cause near-term volatility. Longer term implications however, will depend on whether results changes expectations in corporate earnings, economic growth or interest rates.2
There are three possible anticipated scenarios related to these elections:
The House appears more likely to change hands than the Senate, but the result is far from certain.
As with all political events, rather than positioning portfolios around a particular political outcome, we focus on how developments might affect investment fundamentals. Importantly, markets often react not only to the election results, but to how those results compare with expectations. An anticipated outcome may already be reflected in asset prices, while a surprise could trigger a more pronounced reaction.
As a rule, the first market move off the back of a result is not a reliable indicator for the longer-term investment implications. We saw this example when President Trump was first elected in 2016, and overnight S&P 500 futures fell by almost 5%. However, the next trading day, the S&P 500 was up around 1% and continued to gain over the following year. The rise cannot be attributed solely to the election, but it illustrates the risks of making long-term investment decisions based on short-term market movements.
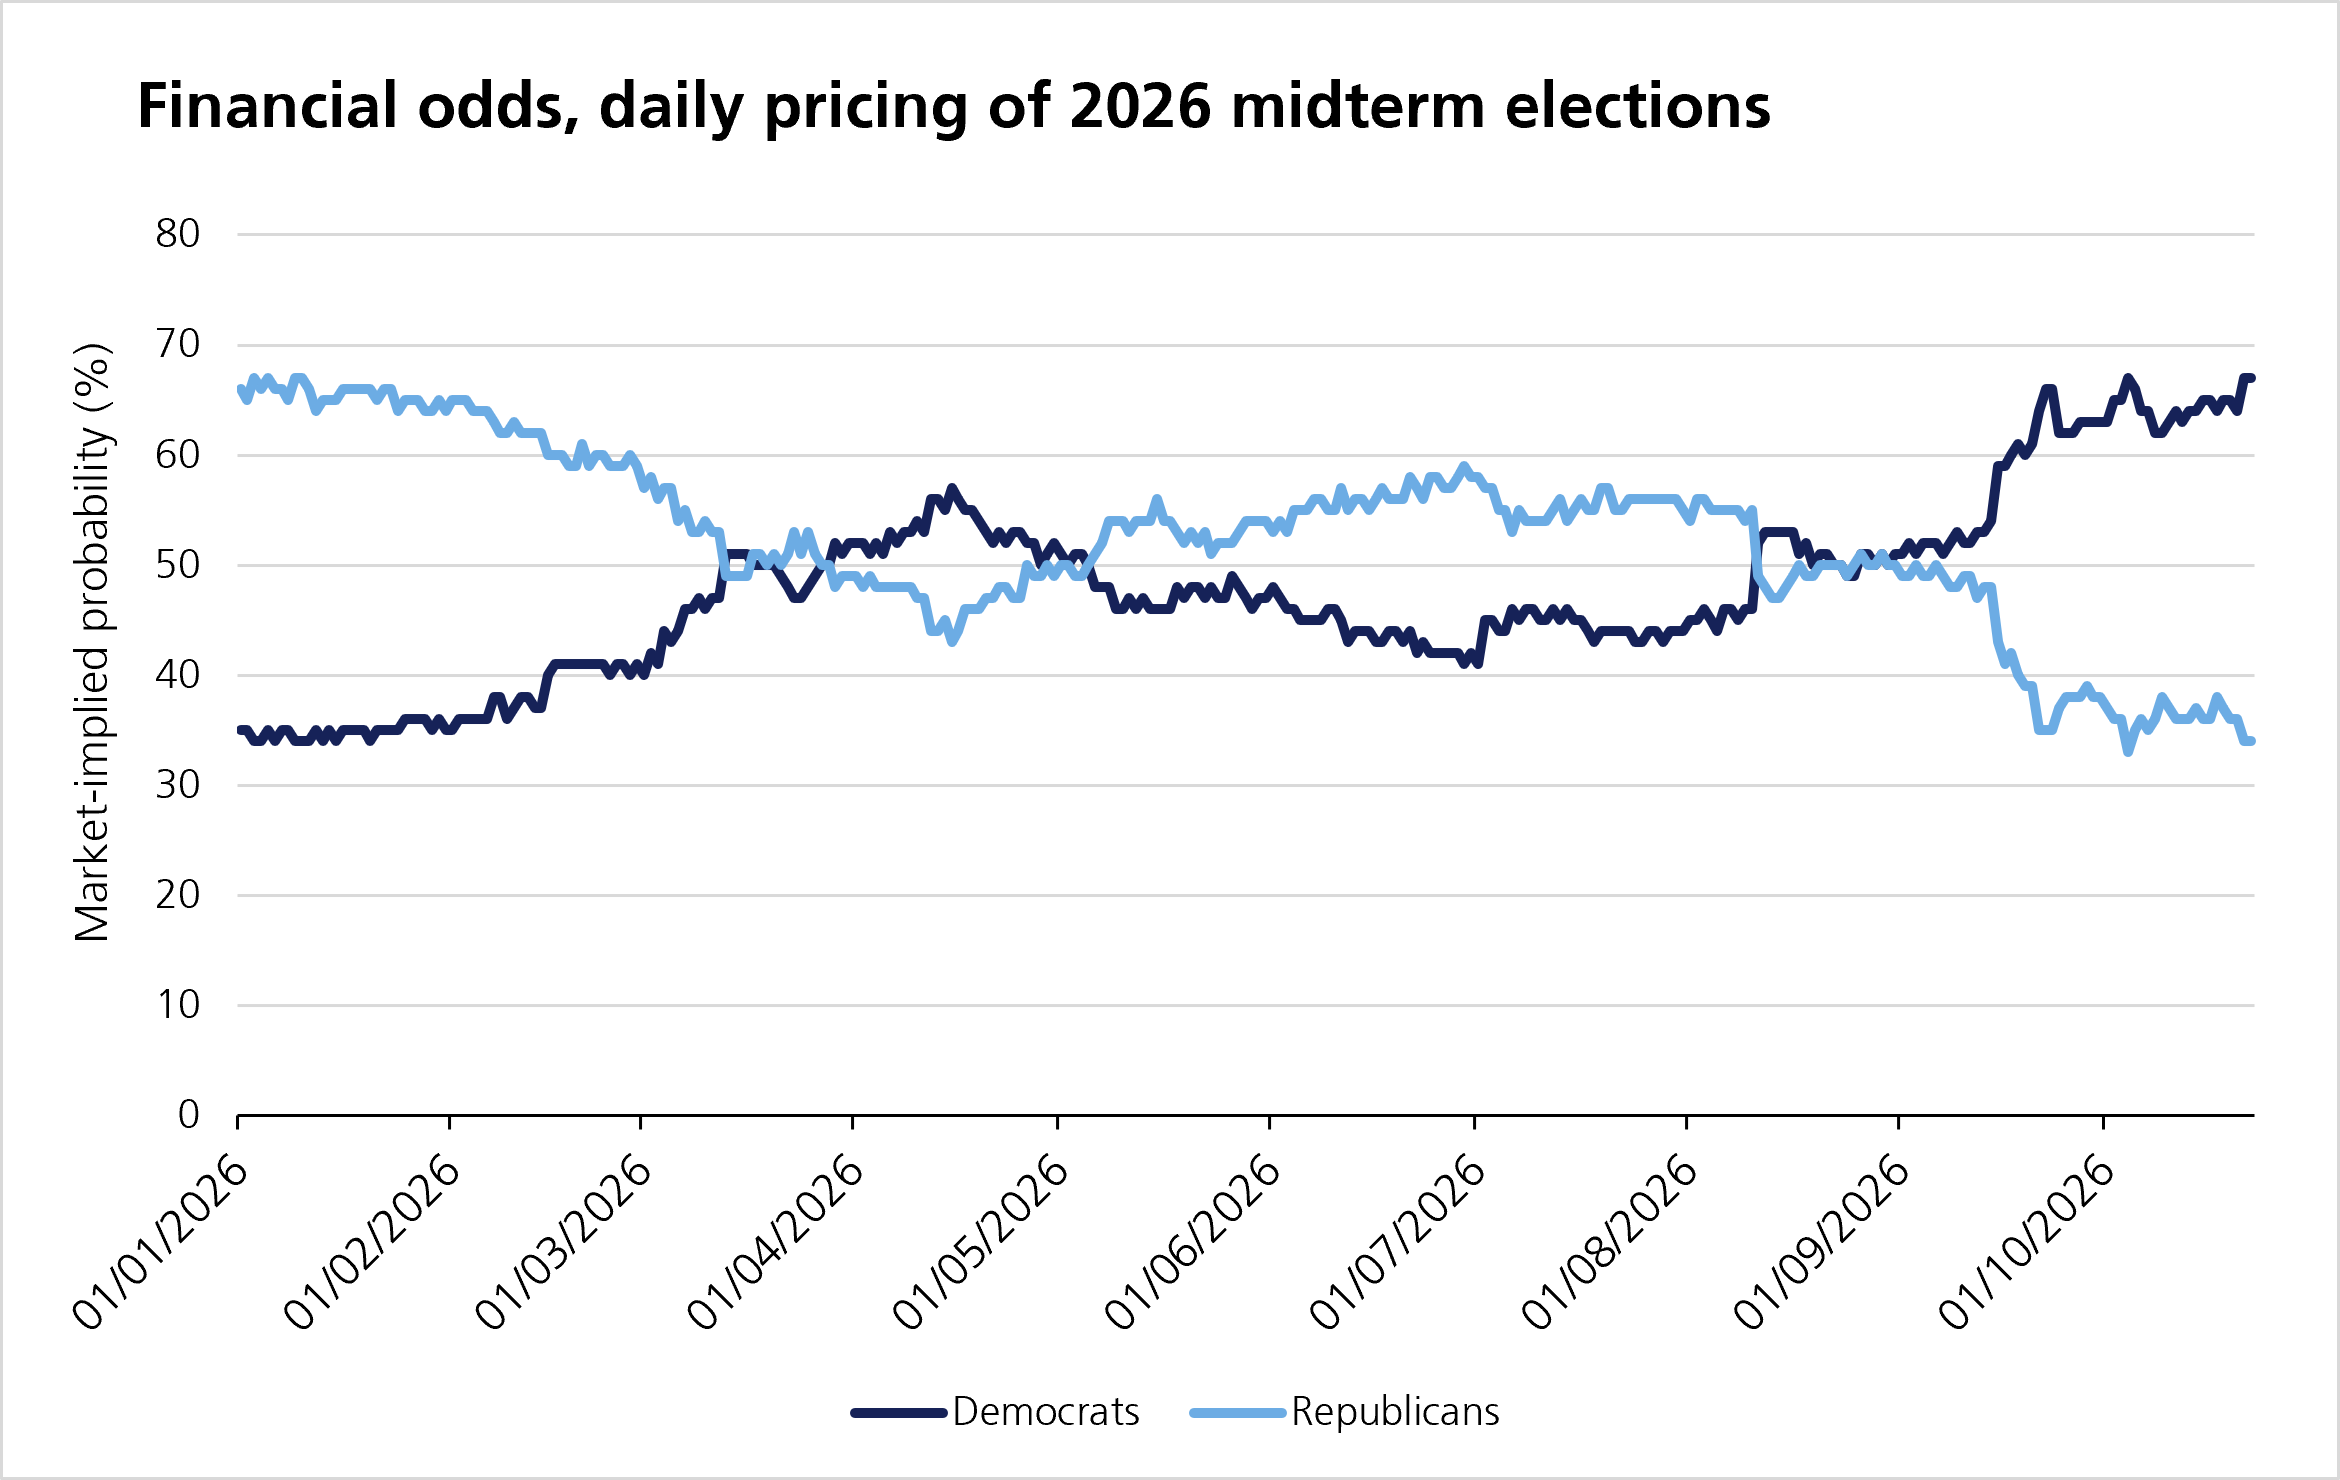
The president’s party has lost House seats in 20 of the past 23 midterm elections, by an average of 27 seats. With a narrow Republican majority and approval ratings under pressure, the House looks vulnerable. The Senate is more difficult to judge: 35 seats are being contested and Democrats would need a net gain of four seats to take control.3 A small number of close races could therefore determine whether the result is a gridlock or a sweep. Prediction-market prices in September and early October favoured Democrats in both chambers, more strongly in the House than the Senate. However, these are only a snapshot of predictions rather than any reliable forecast.
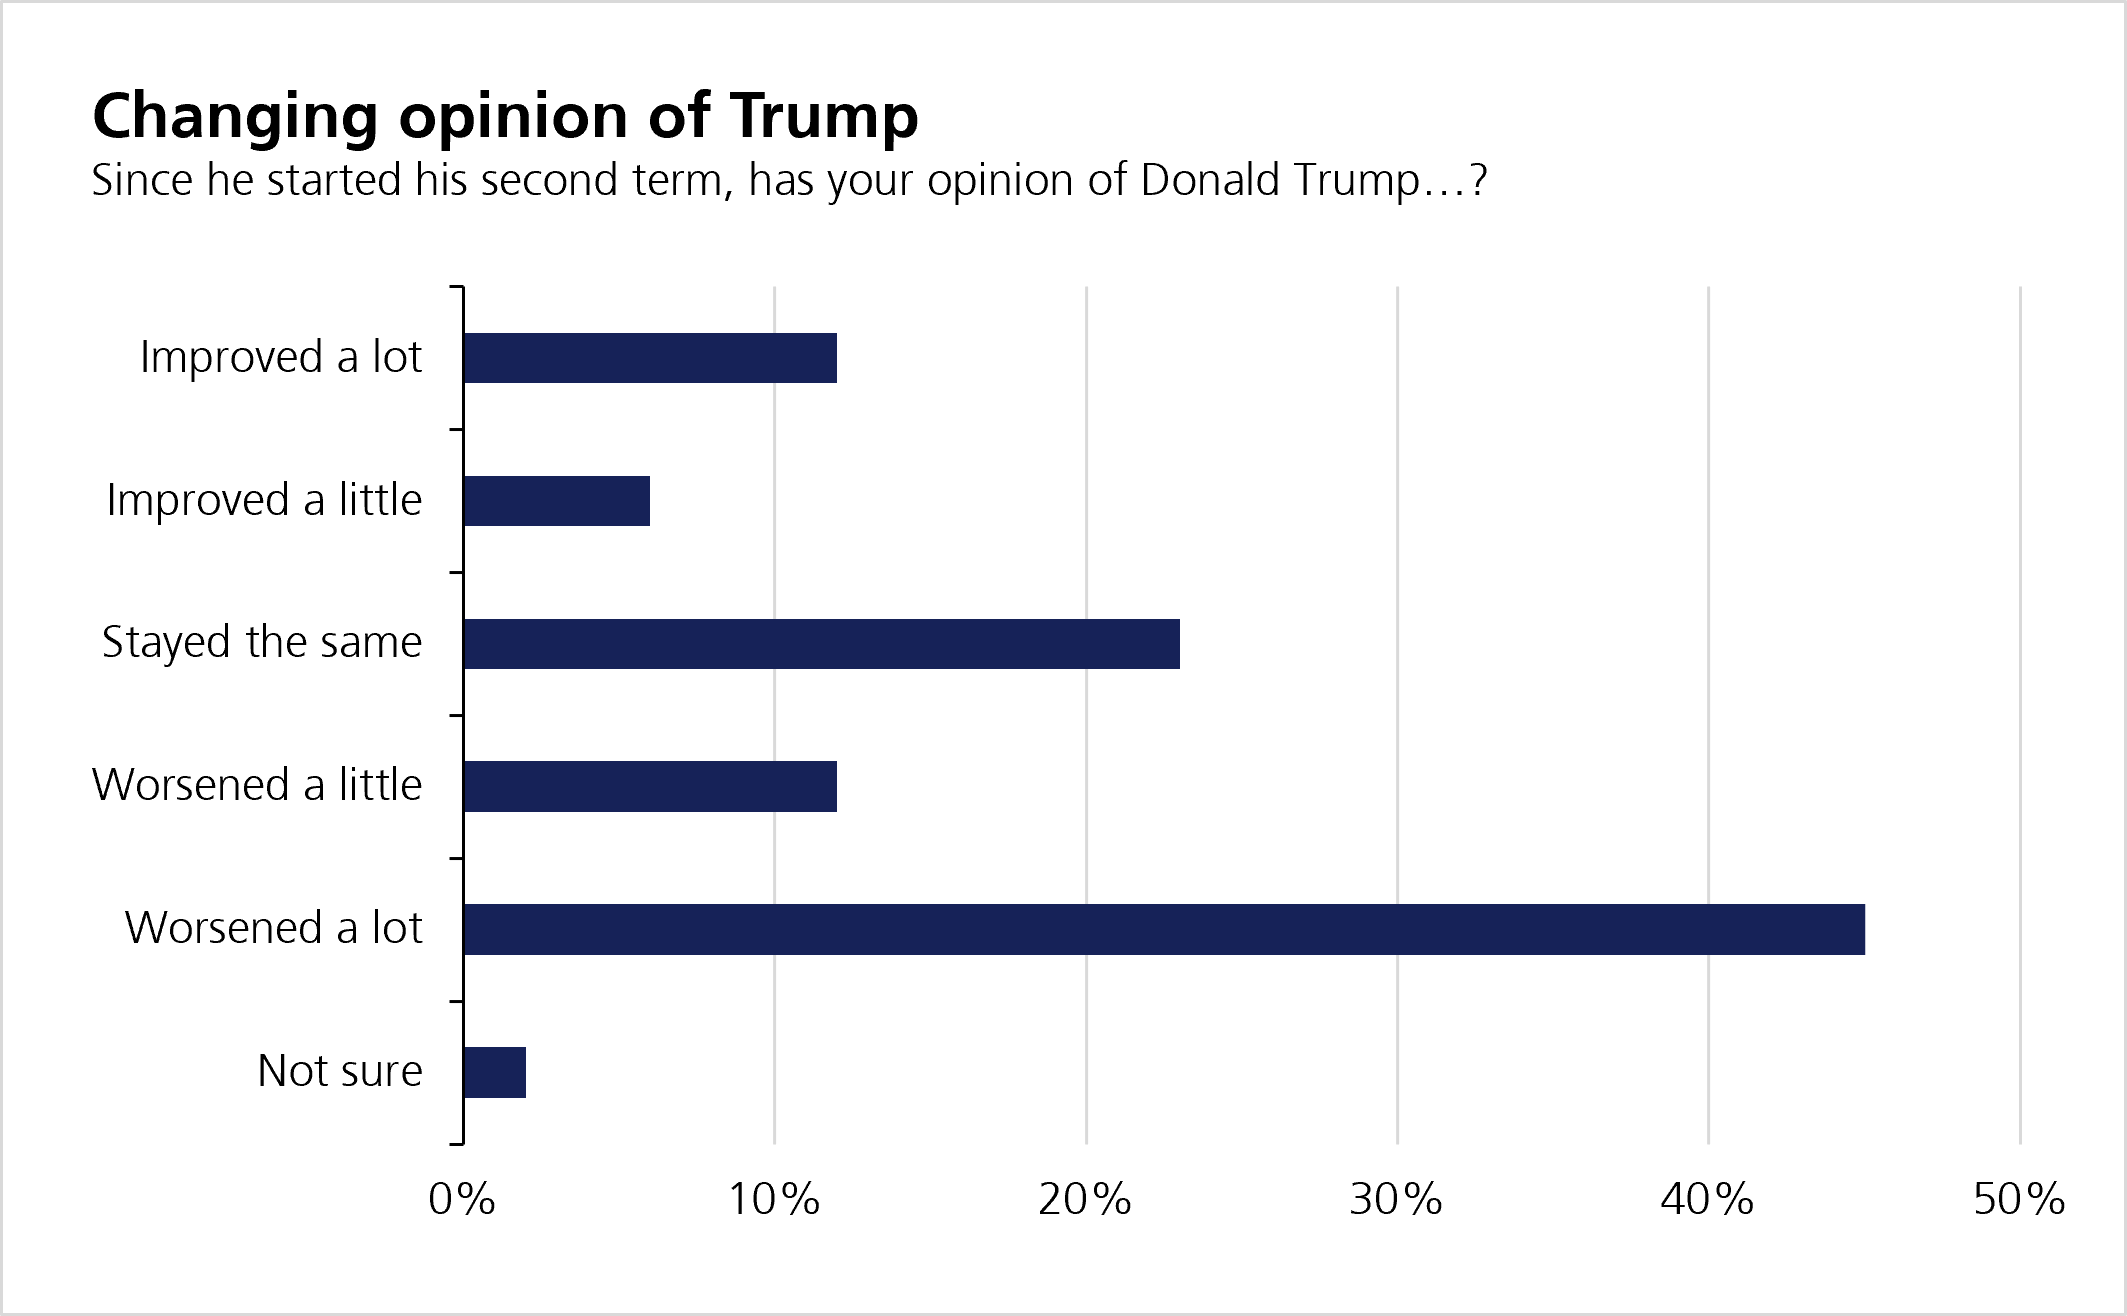
Approval ratings add to the challenge Republicans face in retaining the Senate. Pressure on household budgets, particularly fuel, borrowing costs and inflation, may be influencing voters, along with healthcare affordability. President Trump’s enthusiastic support for AI and light-touch regulation may be at odds with voters who have concerns over safeguarding and data-center development. Additionally, those who expected less US involvement in overseas conflicts may also be uneasy about events in the Middle East.4
If we witness a Blue Wave, Democrats could resist further tax cuts, protect healthcare funding and slow deregulation. There could also be more scrutiny of AI businesses and data-centre development, although new restrictions are far from certain. Even with a Democratic majority in both chambers, the president can still veto legislation. Overriding a veto requires a two-thirds majority in both the House and Senate, which Democrats are unlikely to have. He would also retain considerable authority over trade and foreign policy.
If it is Gridlock, major domestic legislation would be hard to pass. That could constrain any large spending packages, including proposals for tariff-funded payments to households, which would need congressional approval. Funding negotiations could still be contentious. With less room to act at home, the President could use tariffs to press other countries or put more effort into a diplomatic outcome in the Middle East. Neither option is a certainty but decisions in those areas could still affect inflation and market confidence.
A continued Republican majority, the most unexpected outcome, would give the current administration more room to pursue its existing tax and regulatory priorities, maintaining the lighter-touch approach to AI regulation. That might support parts of the technology sector, although company earnings and valuations would still matter more.5
The result of the midterms may indicate how each party will position themselves going into the next presential race, rather than predict the winner. Democrats will be looking at whether more progressive candidates gain ground or if moderates do better. Republicans will be watching whether candidates aligned to President Trump may win or if a different approach has broader appeal.6 Neither party though should assume a good midterm performance carries into 2028.
The implications of any political event for portfolios is always broader than identifying the list of possible winners or predicting outcomes. We monitor our US equity and sector exposure on an ongoing basis, assessing how changes in growth, inflation and interest-rate expectations could affect returns.
If markets fall but company earnings remain resilient, valuations may become more attractive. Equally, an initial rally may prove short-lived if higher bond yields or weaker fundamentals undermine investor confidence. Political headlines might drive short term sentiment, but any decisions should remain grounded in longer term discipline.
For all the discourse, these midterms may matter less to long-term investment decisions than the headlines suggest as they often tell us more about how far the administration can pursue its domestic agenda than the direction of the market. Time will tell whether the midterms prove to be a turning point or simply a noisy intermission.
This communication is provided for information purposes only. The information presented herein provides a general update on market conditions and is not intended and should not be construed as an offer, invitation, solicitation or recommendation to buy or sell any specific investment or participate in any investment (or other) strategy. The subject of the communication is not a regulated investment. Past performance is not an indication of future performance and the value of investments and the income derived from them may fluctuate and you may not receive back the amount you originally invest. Although this document has been prepared on the basis of information we believe to be reliable, LGT Wealth Management UK LLP gives no representation or warranty in relation to the accuracy or completeness of the information presented herein. The information presented herein does not provide sufficient information on which to make an informed investment decision. No liability is accepted whatsoever by LGT Wealth Management UK LLP, employees and associated companies for any direct or consequential loss arising from this document.
LGT Wealth Management UK LLP is authorised and regulated by the Financial Conduct Authority in the United Kingdom.