On Thursday, the Bank of England (BoE) raised its main interest rate from 3.75% to 4%, its first increase in more than three years, voted by a majority of 8-1 votes.1 It came just over a week after Chancellor John Healey's first Budget. These two events signalled two very different messages to households and savers.
Typically, when central banks raise interest rates, the savers benefit and borrowers feel the pinch. The higher interest rates add further costs for borrowers - mortgage payments rise and businesses must pay more to fund themselves, which tends to slow the economy. Savers should be the beneficiaries, as higher rates ought to mean better returns on cash over time and incentivise saving over borrowing. In last week’s Budget, however, the government took a different approach, announcing an increase in the tax on savings income for the second year running.
This week, we look at what the Budget changed, why higher rates have been slow to reach savers in recent months, and why the tax treatment of gilts (UK government bonds) may suit some investors better than cash.
The Budget on 28 October was the first under Prime Minister Andy Burnham, whose government took office in July. Healey described it as offering households "breathing space", with help on energy and fuel costs and small tax increases on savings and property income.2 That came as a relief to investors who had been bracing for tougher measures. In the run-up, press reports had suggested an alignment of Capital Gains Tax with Income Tax, and the introduction of a broader wealth tax and exit taxes on those leaving the UK.3
Seemingly, markets took the Budget delivery calmly. Yields on 10-year gilts – the annual interest cost of borrowing for ten years – edged down to around 5.32% on the day, after reaching a 19-year high of 5.53% in early October.4 That is a welcome change after the volatility that followed the 2022 "mini-budget" under then Prime Minister Liz Truss, when unfunded tax cuts triggered a sharp sell-off in gilts and forced the BoE to intervene. Since then, investors have been quick to demand a higher yield whenever the UK's fiscal plans look uncertain. By avoiding large unfunded measures, the Budget did not add to that pressure while rising inflation has already been pushing yields higher. The relatively muted reaction suggests investors were more focused on the absence of any fiscal surprises than on any major changes to the UK outlook.
Consumer price inflation (CPI) rose to 3.5% in the 12 months to September, from 3.1% in August, driven largely by transport costs, with diesel at its highest price since July 2022.5 On Thursday, the BoE updated its forecasts and now expects inflation to peak at 4.9% in the second quarter of next year, up from the 3.2% peak it forecast in July, as higher energy costs feed through. Governor Andrew Bailey said the rise "shouldn’t be seen as the first in an inevitable long sequence of hikes", but warned it was unlikely to be the last unless the conflict in the Middle East is resolved. Markets now price roughly a 50% chance of another increase in December.
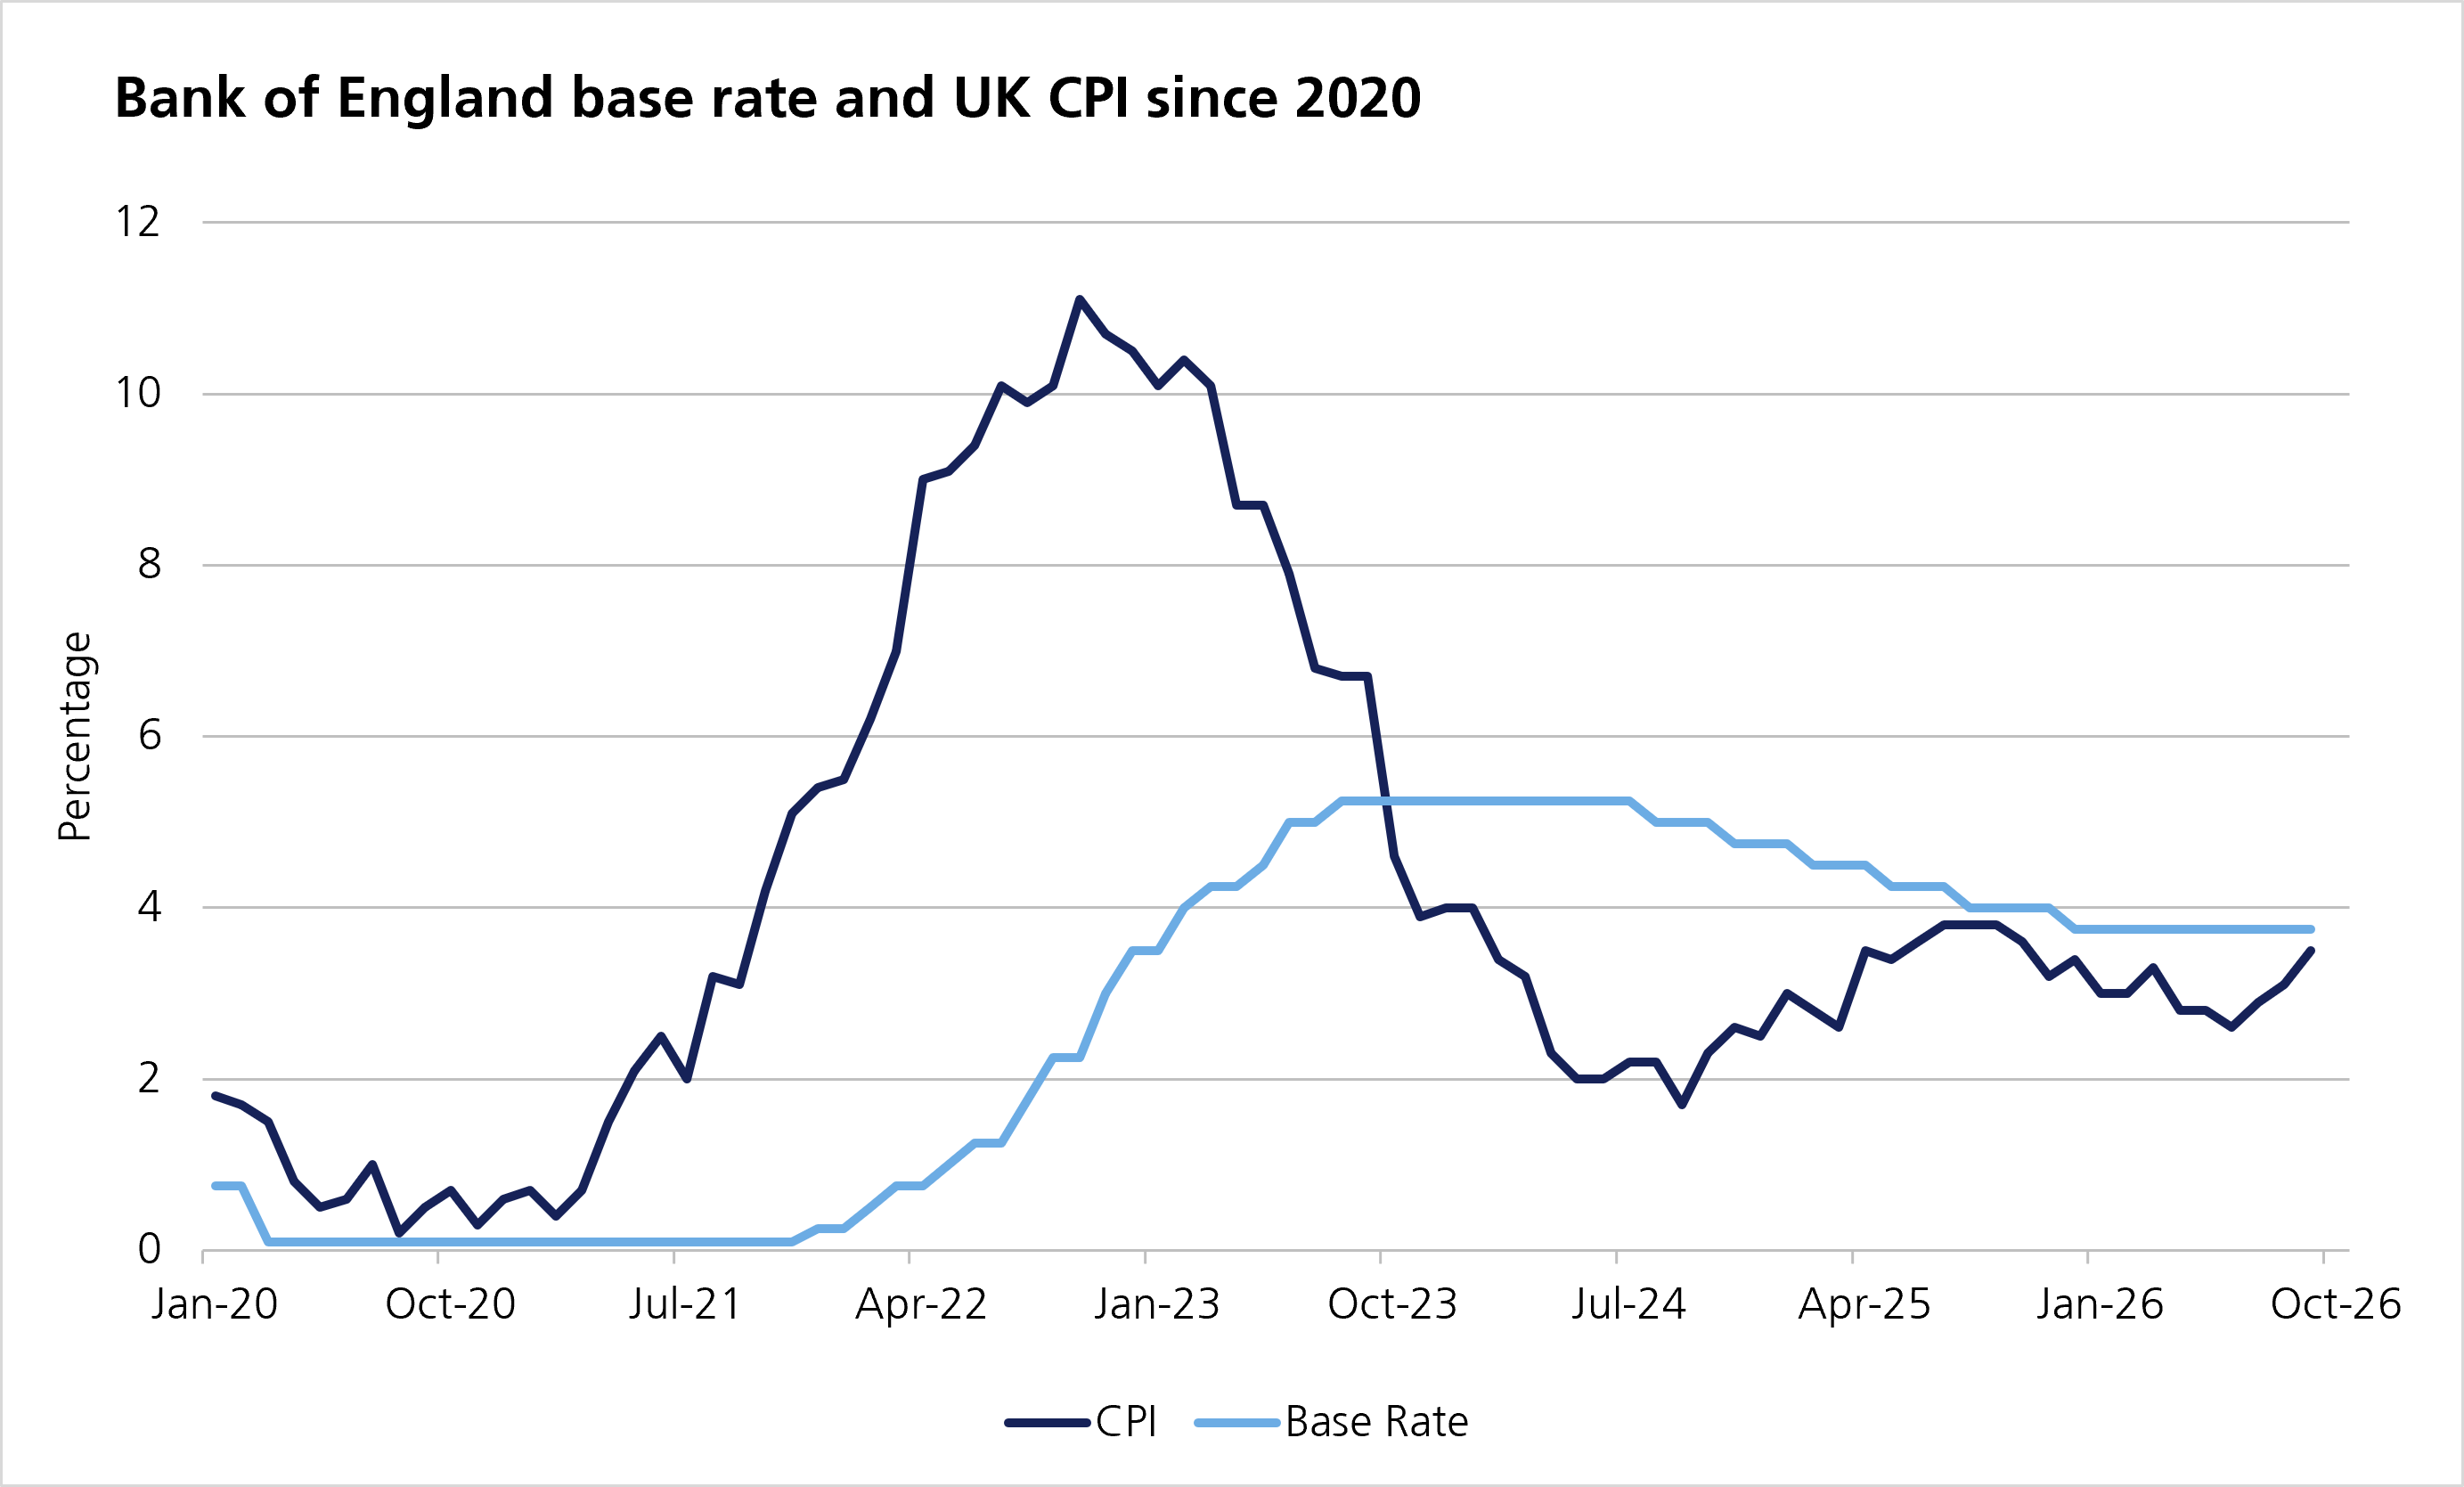
Savers have yet to feel the full benefit of higher interest rates. A higher Bank rate does not automatically translate into a high rate on your accounts and in fact, banks have been slow to pass higher rates on. The average easy access savings account paid 2.53% in September, unchanged for a third month and well below the BoE's main interest rate of 3.75% at the time. With inflation at 3.5%, money in that account is losing purchasing power even before tax. As an illustration, a saver with £10,000 in such an account would have earned about £253 over a year, while keeping pace with prices would have needed about £350. Fixed-rate accounts have fared better, with the average one-year rate rising from 3.79% in March to 4.24%.5
The outlook is further complicated for savers as the Budget also added further pressure on them. Last year, Rachel Reeves announced a 2% increase in the tax on savings income from April 2027. Healey has added another 2 percentage points, so interest above the personal savings allowance – the amount a taxpayer can earn each year tax-free – will be taxed at 24%, 44% and 49% for basic, higher and additional-rate taxpayers respectively.6
As an illustration, a higher-rate taxpayer with a one-year fixed account paying 4.24% would keep around 2.37% after tax from April 2027, which is below current inflation. There was one piece of good news as Healey reversed his predecessor's plan to cut the annual cash Individual Savings Account (ISA) allowance from £20,000 to £12,000, so cash held inside an ISA is unaffected. Larger balances held outside one are not.
This is where we believe gilts could become more fashionable, as gilts held directly are taxed differently. Their coupons – the regular interest payments – count as savings income and will face the higher rates from April 2027. Any capital gain on gilts, however, including the rise in price as a gilt approaches repayment at face value, is exempt from capital gains tax.
The exemption matters most for gilts that were issued when interest rates were very low. These gilts pay small coupons and trade below face value, so most of the return comes from the price rising towards face value at maturity, which is tax-free. BoE staff research published in January found that individual investors' demand for gilts has grown when yields rise relative to savings rates, with the tax exemption a significant driver, although the effect on the wider market has been limited.
Consequently, the effects of these policies raise revenue for the government through higher taxes or increase the demand for gilts, both of which may, at the margin, help to contain borrowing costs.
Taken together, the past few weeks have given savers mixed signals. Higher interest rates should, in principle, help savers. For cash held outside an ISA, though, banks passing on rises slowly, inflation above 3% and higher tax from April 2027 may make it hard to keep pace with rising prices, particularly for higher-rate taxpayers.
For investors who have already used their ISA allowance, we believe the tax treatment of gilts is worth careful consideration. Lower-coupon gilts, where more of the return comes as a tax-free capital gain, can offer higher after-tax returns than cash for higher-rate taxpayers. Therefore, it is worth reviewing how your cash is held before April 2027 and speaking to your investment manager to seek the best advice for your circumstances.
This communication is provided for information purposes only. The information presented herein provides a general update on market conditions and is not intended and should not be construed as an offer, invitation, solicitation or recommendation to buy or sell any specific investment or participate in any investment (or other) strategy. The subject of the communication is not a regulated investment. Past performance is not an indication of future performance and the value of investments and the income derived from them may fluctuate and you may not receive back the amount you originally invest. Although this document has been prepared on the basis of information we believe to be reliable, LGT Wealth Management UK LLP gives no representation or warranty in relation to the accuracy or completeness of the information presented herein. The information presented herein does not provide sufficient information on which to make an informed investment decision. No liability is accepted whatsoever by LGT Wealth Management UK LLP, employees and associated companies for any direct or consequential loss arising from this document.
LGT Wealth Management UK LLP is authorised and regulated by the Financial Conduct Authority in the United Kingdom.